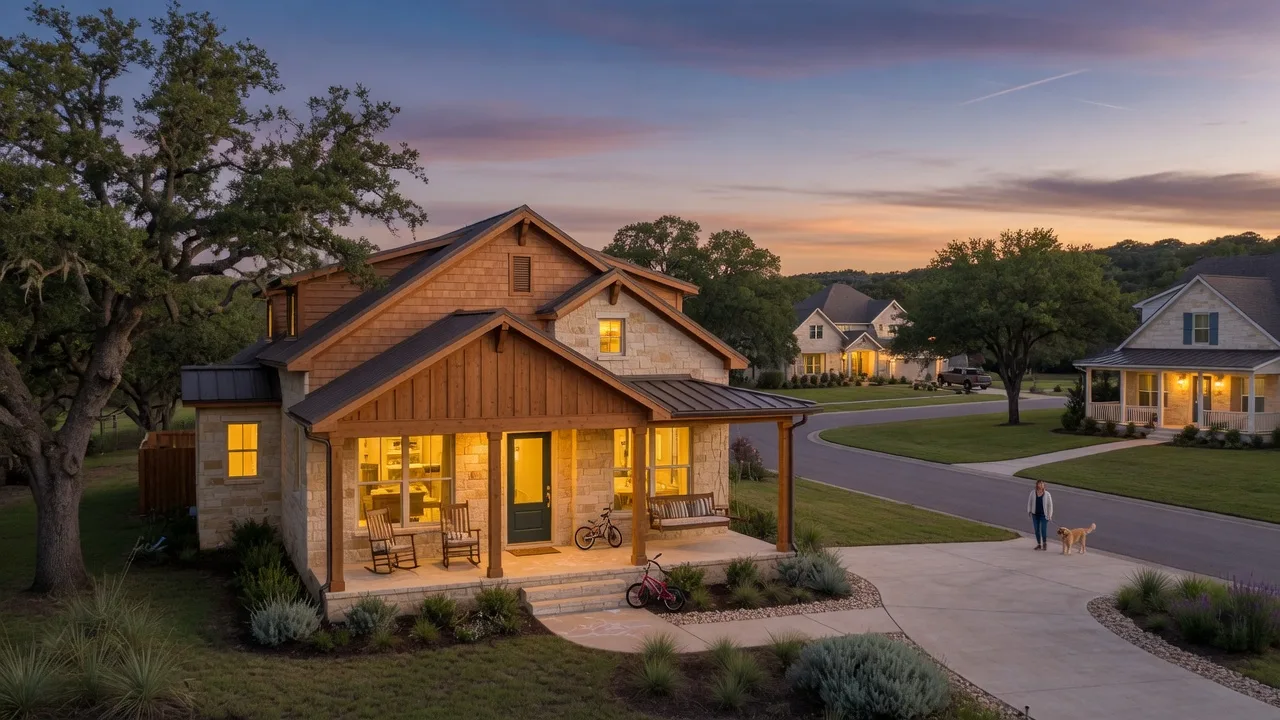
Here is the honest version of the conversation you have probably been having with yourself: the housing math that used to work in California stopped working, and the house that fits your life keeps getting further away. This page is for that exact moment. The short version, up front: for somewhat more than the rent on a two-bedroom apartment in San Jose, a qualified buyer can often step into a three- or four-bedroom house in the Texas Hill Country, with a real lot, a garage that fits the cars, and room for the rest of life [14][15]. We will also be straight about what Texas costs, because property taxes, insurance, the summers, and the distance from family are real, and a decision this big deserves the whole picture, not just the pretty part. Then we will show you what the deal looks like at $600,000, $800,000, and $1.2 million, with the numbers in front of you and the sources at the bottom so you can check the work. That is the plan: we understand the concern, we show you the trade, and you get to decide.
The Whole Article in One Paragraph
Every home described below is a composite shopping profile, not a specific listing. To build each profile, I reviewed current and recent market inventory within each price band for the named community and compared living area, lot size, age, property type and recurring amenities. Citywide median-price and home-value data provide market context but do not by themselves determine the composite. No addresses, no inventory plays, no bait. Ranges, not false precision, and honest tradeoffs.
How to Keep the Win
The deal is real, and it is also conditional. These four lines are the fine print, laid out honestly so nothing surprises you after closing day.
- 1
Property taxes are the price of admission.
Texas has no individual state income tax. Texas relies more heavily on sales and property taxes; the combined state-and-local sales-tax rate is 8.25 percent in many of these communities. For initial planning, I use roughly 1.7 to 2.1 percent of market value per year before exemptions as a broad Hill Country budgeting range. That is only a screening estimate. Actual tax is determined from the property's taxable value and the rates imposed by its specific taxing units. Some newer developments also carry MUD taxes or PID assessments. Texas school districts must provide a $140,000 general residence-homestead exemption. A homeowner who qualifies as age 65 or older or disabled receives an additional $60,000 school-district exemption, bringing the mandatory school-district exemption to $200,000. Other local exemptions may also apply [33]. For a qualifying residence homestead, the appraisal limitation generally restricts annual growth in appraised value to 10 percent, subject to the statutory rules for when the limitation begins and for new improvements [34]. You can protest a value you believe is wrong. The full walk-through is in the Proposition 13 vs Texas property tax guide [23].
- 2
Insurance is real money, not a footnote.
Texas homeowners insurance averaged $3,489 per year statewide in 2025, according to the current Texas Department of Insurance homeowners-market data [22]. That is a statewide average, not a quote for a particular Hill Country property. Wind and hail deductibles can differ from the deductible for other covered losses and may be expressed as either a dollar amount or a percentage of the insured value, depending on the policy. Standard homeowners insurance generally does not cover flood damage. Near the Guadalupe, Comal, or Medina rivers—or any creek—check the FEMA flood map for the exact address and obtain a property-specific flood-insurance quote before you commit [31]. NFIP coverage ordinarily carries a 30-day waiting period, although important exceptions apply, including coverage purchased in connection with making, increasing, extending, or renewing a mortgage [32]. Get property-specific homeowners and flood quotes before the option period ends.
- 3
The heat is not a rumor.
June through September is genuinely hot, the air conditioning runs hard, and the summer electric bill is the one that surprises newcomers. Budget the utility line and buy a house with good insulation and shade.
- 4
Distance from family is the line no spreadsheet fixes.
The flight to California runs three to four hours, not a commuter hop. Look at this one honestly and on purpose, before the price-and-space advantage carries too much weight in the decision. The house will be here either way.
Same Money, Two States
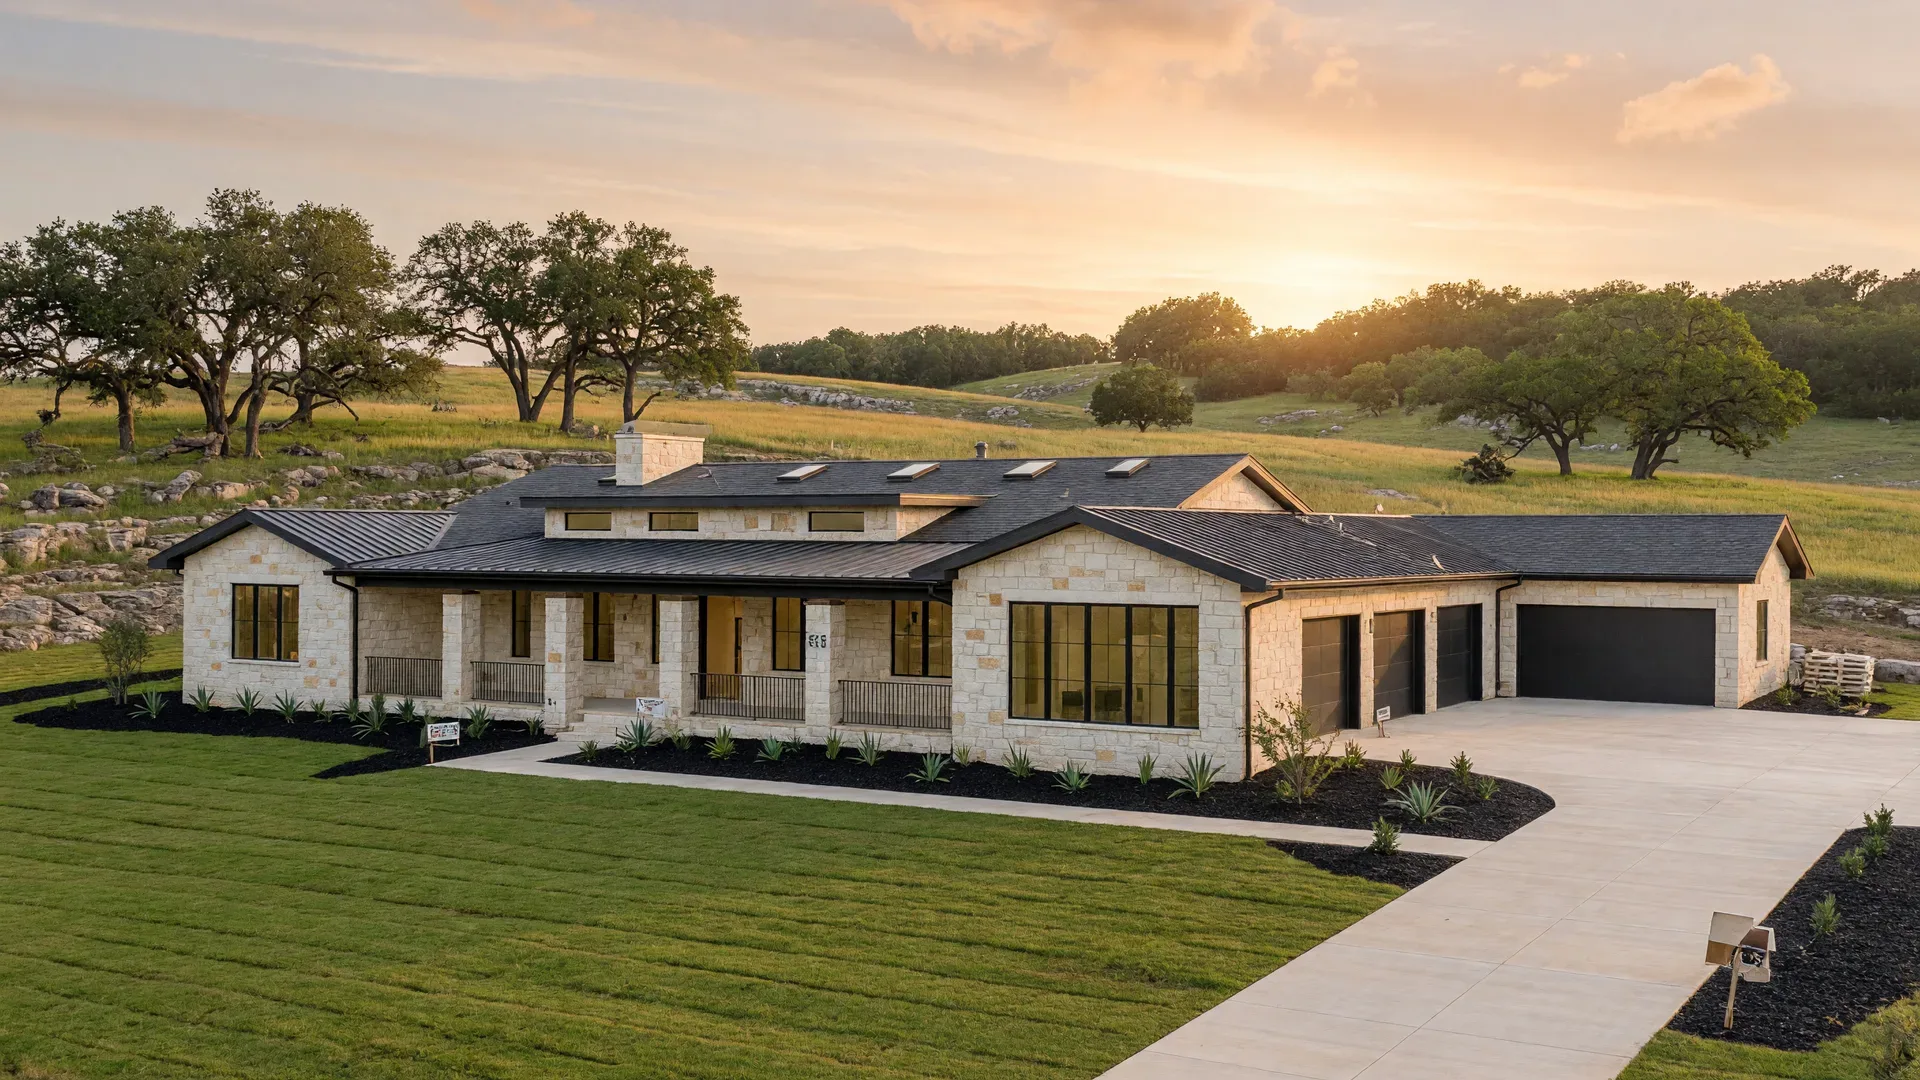
These two illustrations carry more weight than any paragraph in this article. Both are representative images, not listings. Left is what a middle budget buys in a coastal California market. Right is what the same money buys in the Texas Hill Country.
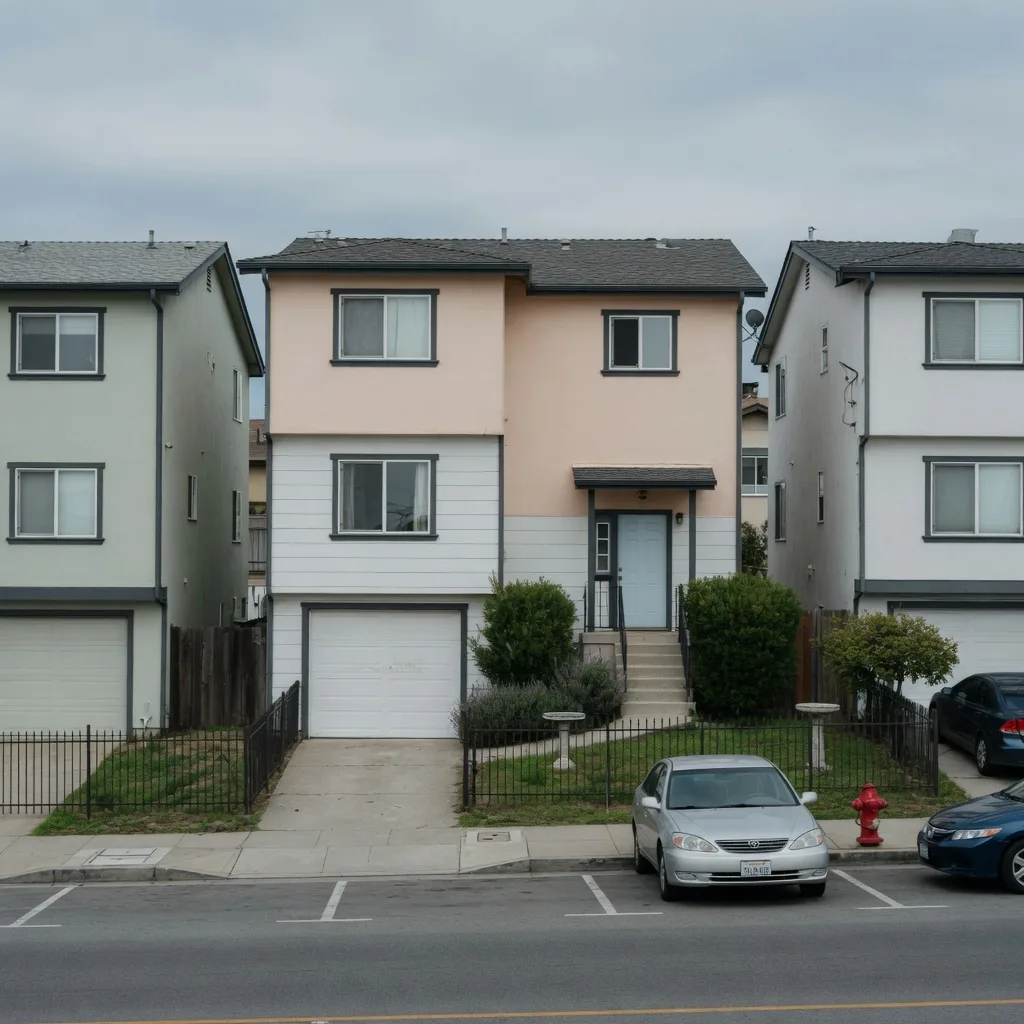
California side
Attached and compact, often with shared walls, HOA dues and substantially less private outdoor space. At these budgets, buyers in the coastal California markets examined here are far more likely to be shopping condominiums, townhouses or smaller and older detached homes.
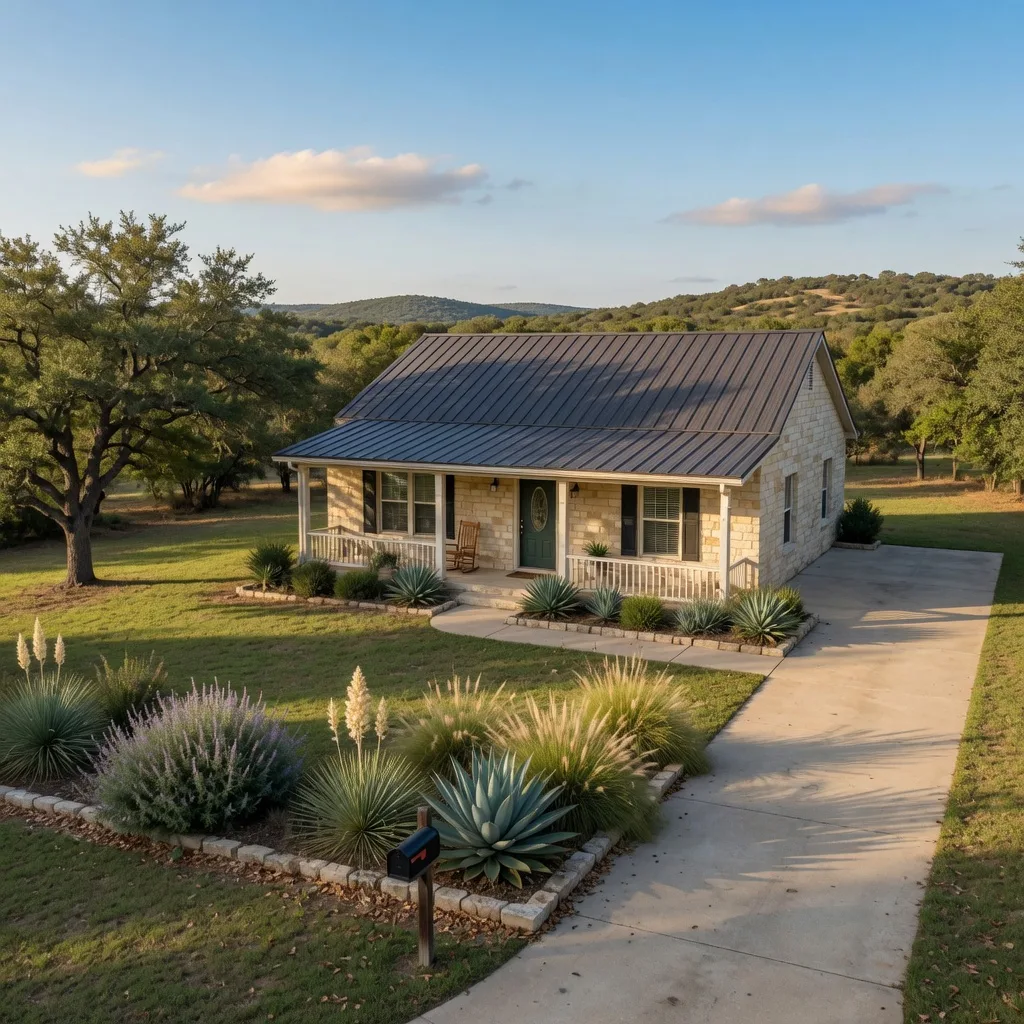
Texas side
Detached, generally larger, and often with a private yard measured in fractions of an acre. At the same budget, the Hill Country frequently shifts the search from attached housing to detached single-family ownership.
HOW THE REPRESENTATIVE HOMES WERE BUILT
The homes below are composites, not listings. To build each profile, I reviewed current and recent market inventory within each price band for the named community and compared living area, lot size, age, property type and recurring amenities. Citywide median-price and home-value data provide market context but do not by themselves determine the composite. Because inventory changes continuously, treat each profile as a realistic shopping target rather than a promise that every listed feature will be available at that price. Inventory review was conducted in late September 2026; because active and recently sold inventory changes continuously, these profiles are snapshots of the market rather than guaranteed feature sets.
Budget One: $600,000
At $600,000, the budget sits above the current Zillow Home Value Index typical-home-value benchmark in five of the six communities examined here. As of August 31, 2026, Zillow reports typical home values of approximately $557,000 in Boerne, $702,000 in Fair Oaks Ranch, $466,000 in Helotes, $476,000 in Bulverde, $346,000 in New Braunfels, and $354,000 in Kerrville. On that single, consistent measure, Fair Oaks Ranch is the only one of the six whose typical value remains above $600,000.
Those figures are Zillow ZHVI typical-home values, not transaction medians. Recent sale-price medians from Redfin can differ materially—especially in smaller markets where the mix of homes sold in a given period can move the median sharply. I therefore use ZHVI for the six-community apples-to-apples benchmark and current listing inventory to build the illustrative shopping profiles below.
| Community | Illustrative shopping profile | Size | Lot | Beds/baths | Schools |
|---|---|---|---|---|---|
| Boerne | Established stone or brick ranch; examples may sit near town or in an established neighborhood | 2,200-2,700 sq ft | 0.5-1 acre | 3-4 bed / 2-3 bath | Boerne ISD, rated A overall in 2026; the district reports seven consecutive A ratings [18][19] |
| Fair Oaks Ranch | Patio home or slightly older single-family; the newer, larger homes start higher in this market | 1,900-2,400 sq ft | 0.25-0.5 acre | 3 bed / 2-2.5 bath | Boerne ISD for most addresses; some parcels fall to Northside ISD or Comal ISD, so confirm by exact address [21] |
| Helotes | A larger home on a tree-lined lot with Hill Country views; at this price you are shopping the upper half of the Helotes market | 2,800-3,400 sq ft | 0.5-1 acre | 3-5 bed / 2-4 bath | Northside ISD, rated C overall in 2026; campus ratings vary widely, so check the specific schools for the address [29] |
| Bulverde | Newer four-bedroom with the quiet of the Hill Country and the US 281 commute to San Antonio | 2,400-3,000 sq ft | 0.5-1 acre | 4 bed / 3 bath | Comal ISD, rated B [20] |
| New Braunfels | New or newer house that may include a neighborhood pool, with the Comal and Guadalupe rivers minutes away | 2,200-2,800 sq ft | 0.25-0.5 acre | 3-4 bed / 2-3 bath | New Braunfels ISD or Comal ISD, depending on the address; both rated B in 2026 [20][28] |
| Kerrville | Stone-front home on a big lot, with the Guadalupe River through town and San Antonio about 65 miles southeast | 2,300-3,000 sq ft | 0.5-1+ acre | 3 bed / 2 bath | Kerrville ISD, rated B overall in 2026; campus ratings vary, so verify the assigned campus for the specific address [30]. |
Illustrative shopping profiles assembled from current and recent market inventory within each price band; citywide median-price and home-value data provide market context but do not by themselves determine the composite [1][4][5][6][7][8][9][10][39]. Not specific listings; no addresses. Inventory and prices change, so verify current listings at publish time.
Same $600,000, two states
| Where you spend it | What it gets you |
|---|---|
| San Jose | A roughly 900-1,200 sq ft condominium or an aging townhouse. A detached house at this number is essentially off the table; the San Jose median sale price is about $1.4 million, at roughly $858 per square foot [11]. |
| West LA / Westside | An older condominium, often under 1,000 sq ft, with HOA dues. A detached house is not realistic here; the Westside median sale price is about $1.9 million [12]. |
| Orange County | A roughly 800-1,100 sq ft condominium with HOA dues and no yard to speak of; the coastal cities run higher [13]. |
| Texas Hill Country | A roughly 1,900-3,400 sq ft house on a quarter-acre to a full acre: three to four bedrooms, an attached garage, a yard, and your pick of six communities, most in districts rated A or B [1][4][5][6][7][8][9][10][39][18][19][20][28]. |
Budget Two: $800,000
At $800,000 you move from the middle of this market to the top of its mainstream, and the words that start appearing are acre, pool, and gated. Fair Oaks Ranch, where Zillow reports a typical home value of about $702,500 and Redfin reports a recent three-month median sale price of about $718,500, becomes fully reachable at an $800,000 budget. In California, $800,000 is the number where you stop explaining why your place is small and start explaining why it needs work.
| Community | Illustrative shopping profile | Size | Lot | Beds/baths | Schools |
|---|---|---|---|---|---|
| Boerne | New or near-new four-bedroom in a master-planned community, or a large established home that may include a pool and a shop | 3,000-3,600 sq ft | 0.25-1.5 acre | 4 bed / 3-3.5 bath | Boerne ISD, rated A [18][19] |
| Fair Oaks Ranch | The community's signature: a large home on a half-acre to an acre, which may be gated or golf-adjacent | 2,800-3,500 sq ft | 0.5-1 acre | 4 bed / 3-3.5 bath | Boerne ISD for most addresses; Northside or Comal ISD for some parcels [21] |
| Helotes | Gated-community homes in the master-planned areas, which may include a pool and a study | 3,200-3,800 sq ft | 0.5-1 acre | 4-5 bed / 3-4 bath | Northside ISD, rated C overall in 2026; campus ratings vary widely, so check the specific schools for the address [29] |
| Bulverde | Acreage and charm: examples include large homes on one to three acres, and some may offer room for horses, a shop, or both | 3,000-3,500 sq ft | 1-3 acres | 4 bed / 3-4 bath | Comal ISD, rated B [20] |
| New Braunfels | Larger newer home, some near the river or with hilltop views; historic Gruene is nearby | 2,900-3,400 sq ft | 0.5 acre | 4-5 bed / 3-4 bath | New Braunfels ISD or Comal ISD by address; both rated B [20][28] |
| Kerrville | Large home or estate on acreage near the river, with mature oaks; some examples may offer a guest cottage | 2,600-3,200 sq ft | 1-5 acres | 4 bed / 3 bath | Kerrville ISD, rated B overall in 2026; campus ratings vary, so verify the assigned campus for the specific address [30]. |
Illustrative shopping profiles assembled from current and recent market inventory within each price band; citywide median-price and home-value data provide market context but do not by themselves determine the composite [1][2][3][6][8][10]. Not specific listings; no addresses. Verify current listings at publish time.
Same $800,000, two states
| Where you spend it | What it gets you |
|---|---|
| San Jose | A condominium or townhouse of roughly 900-1,200 sq ft. Detached houses at this price are rare, small, and usually need work, and about half of San Jose sales close above list price [11]. |
| West LA / Westside | A condominium with a very real HOA. A house that works as-is sits far above this number [12]. |
| Orange County | A townhouse or condo of roughly 1,100-1,400 sq ft, or a small, older detached house inland; the countywide median runs about $676 per square foot [13]. |
| Texas Hill Country | A 2,600-3,800 sq ft new or near-new house on a half-acre or more: four bedrooms, an office, a garage, and a pool that can be within reach. Fair Oaks Ranch and the Boerne master plans live at this number [1][2][3]. |
Budget Three: $1.2 Million
At $1.2 million you move well into the upper tier of the mainstream market in these six Hill Country communities rather than merely buying a larger version of the median home. In the Hill Country that number buys an estate: custom construction, acreage, a pool, guest quarters, sometimes premium outdoor improvements or guest accommodations [1][2][10]. In California it sits at or below the middle: San Jose's median sale price runs about $1.4 million [11], the Westside's about $1.9 million [12], and Orange County's about $1.2 million countywide, with single-family medians closer to $1.5 million [13]. At $1.2 million in San Jose you are shopping below the current citywide median. Detached choices at that level tend to involve tradeoffs in size, condition, location or some combination of the three. Put the Hill Country sentence next to the California one and read them slowly. That gap, more than any single statistic, is the whole point of this article.
| Community | Illustrative shopping profile | Size | Lot | Beds/baths | Schools |
|---|---|---|---|---|---|
| Boerne | Custom estate with limestone and oak floors; a pool, guest house, or premium outdoor improvements or guest accommodations may be included | 4,000-5,500 sq ft | 1-5 acres | 4-5 bed / 4-5 bath | Boerne ISD, rated A [18][19] |
| Fair Oaks Ranch | Examples include gated or golf-front estates in the country-club sections of the community | 3,800-5,000 sq ft | 1-4 acres | 4-5 bed / 4-5.5 bath | Boerne ISD, Northside or Comal by parcel [21] |
| Helotes | An acre-plus custom home with Hill Country views; examples include gated estates in the upper tier of the Helotes market | 4,000-5,000 sq ft | 1-2 acres | 4-5 bed / 4-6 bath | Northside ISD, rated C overall in 2026; campus ratings vary widely, so check the specific schools for the address [29] |
| Bulverde | Ranch-scale living: examples include large custom homes with horse facilities, a barn, or a shop on acreage | 3,500-5,000 sq ft | 2-10 acres | 4-6 bed / 4-6 bath | Comal ISD, rated B [20] |
| New Braunfels | Custom homes that may feature premium outdoor improvements or guest accommodations, and large acreage spreads near town | 3,500-5,000 sq ft | 1-5 acres | 4-6 bed / 4-6 bath | New Braunfels ISD or Comal ISD by address; both rated B [20][28] |
| Kerrville | Custom homes in the upper tier of the local market may include premium outdoor improvements or guest accommodations | 3,200-4,500 sq ft | 1-5+ acres | 4-5 bed / 3-5 bath | Kerrville ISD, rated B overall in 2026; campus ratings vary, so verify the assigned campus for the specific address [30]. |
Illustrative shopping profiles assembled from current and recent market inventory within each price band; citywide median-price and home-value data provide market context but do not by themselves determine the composite [1][2][10]. Not specific listings; no addresses. Verify current listings at publish time.
A word on river frontage. The Guadalupe, the Comal, and the creeks that feed them are why these properties command a premium, and they are also why the July 2025 flood in Kerr County was so deadly. Before you fall for a riverfront lot, pull the FEMA flood map for the exact address, ask where the home sits relative to the FEMA 1-percent-annual-chance floodplain, often called the '100-year' floodplain, get a flood insurance quote, and review the seller's disclosure and available flood history, and ask specifically about prior flooding, water intrusion and any known 2025 impacts where relevant. A river view from above the floodplain is a very different asset from a river view in it.
Same $1.2 million, two states
| Where you spend it | What it gets you |
|---|---|
| San Jose | A 1,300-1,500 sq ft house, older, that still needs attention. About $200,000 below the median, you remain below the citywide median, so location, condition and lot size become major tradeoffs [11]. |
| West LA / Westside | A condominium or townhouse. Single-family homes here sell well above this number; the median is about $1.9 million [12]. |
| Orange County | An older detached home in some inland submarkets or a larger townhouse, with size, condition and location varying substantially across the county. The countywide median is about $1.2 million, so you compete in the middle, and the coastal cities sit well above it [13]. |
| Texas Hill Country | A 3,200-5,500 sq ft custom home on one to five acres or more; examples may include guest quarters, a pool, or premium outdoor improvements or guest accommodations. At this number you are in the upper tier of these local markets, not the middle [1][2][10]. |
What the Extra Space Does on a Tuesday
Square footage is an abstraction. This is what it actually does to a normal day.
-
A home office plus a guest room
Work gets a door and a desk ten steps from the kitchen. The in-laws or the college kid get their own room, not the couch. Two spaces that can be difficult to fit into a smaller California floor plan can coexist comfortably here.
-
A pool
At the upper budget tiers used in this article, a pool becomes a realistic feature to find in the inventory rather than an automatic budget-breaker. The honest cost of building and maintaining one is its own article, so read the true cost of a Texas pool before you fall in love with the water.
-
A shop or studio
A place for the tools, the projects, the side business, the car you keep meaning to fix. Room to make things is a quality-of-life line most people do not know they are missing.
-
Garden and dog space
A real garden with room to fail at tomatoes and try again. A dog door that leads somewhere. These are the small freedoms that make a house feel like a life.
-
A real yard for kids
Grass that fits a game of catch, a swing set that stays up all season, birthday parties that happen outside without a park reservation. The yard is the room your kids will remember best.
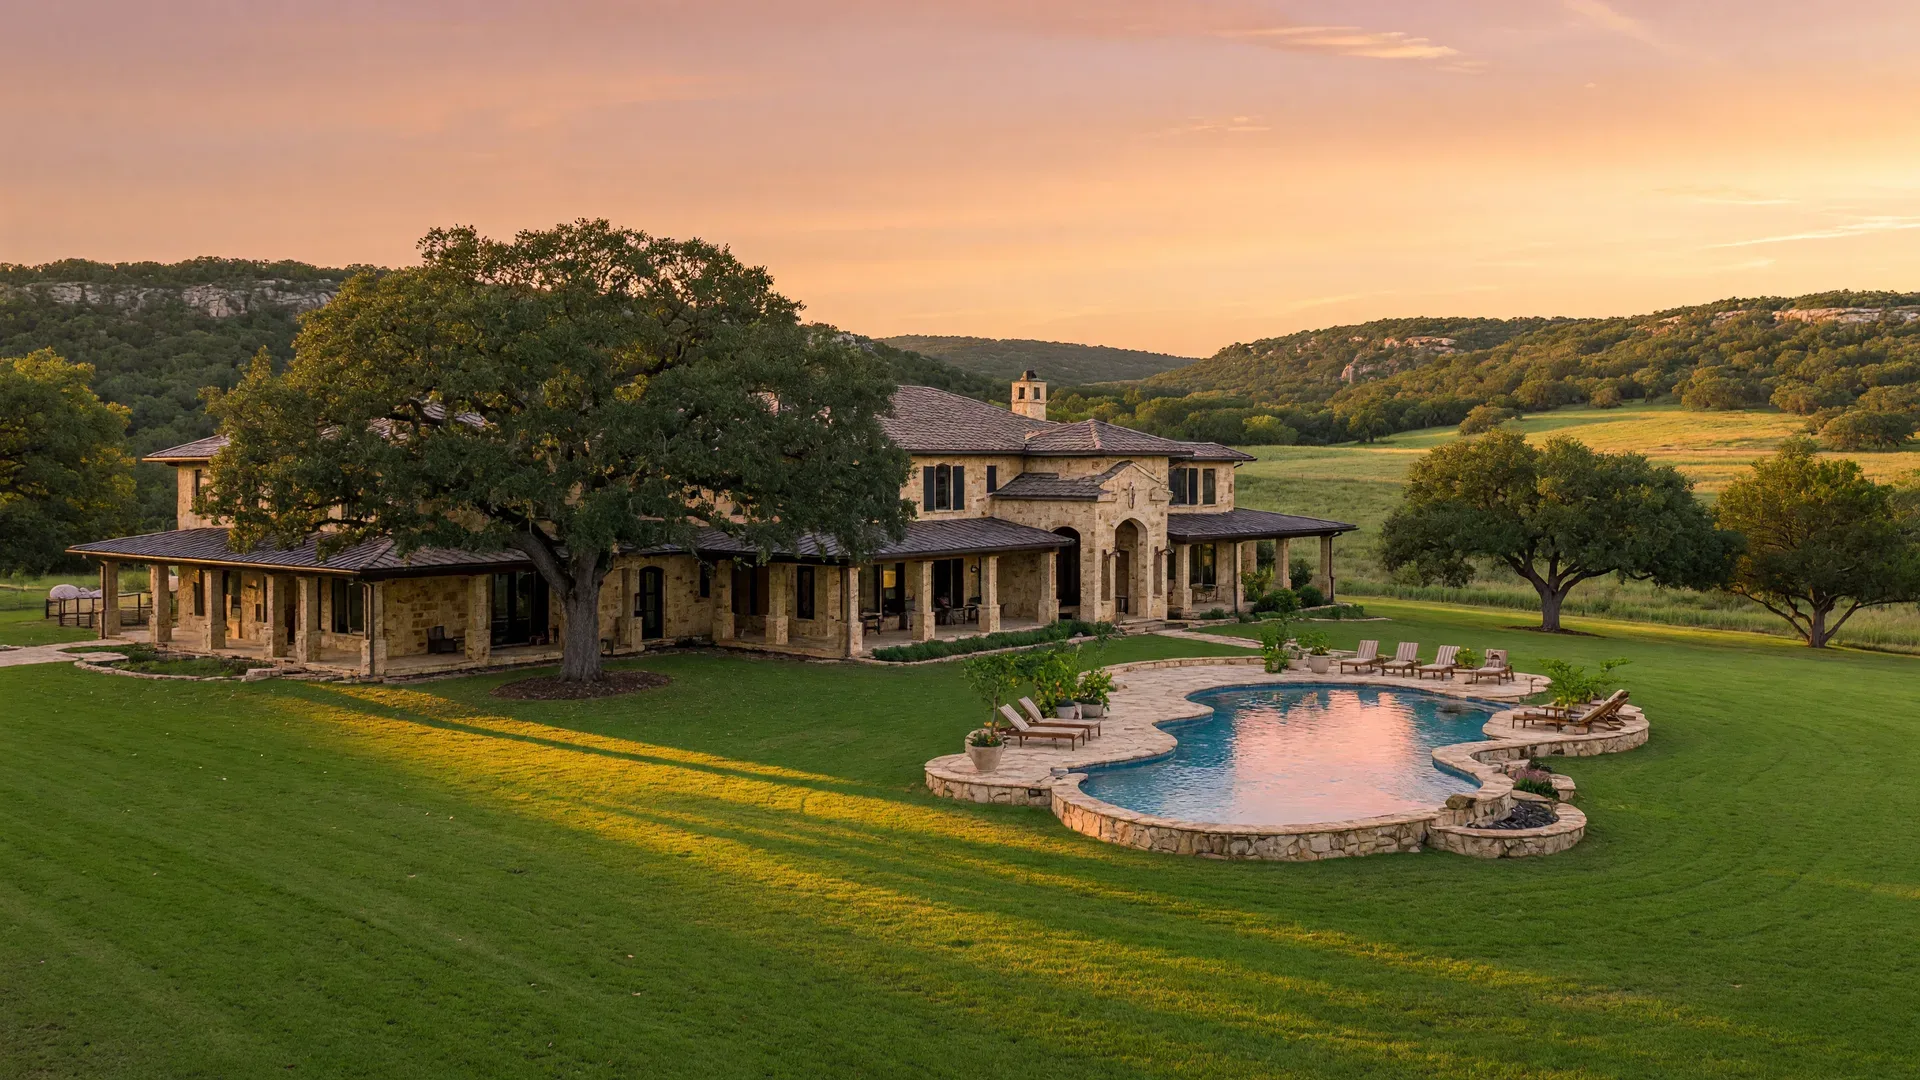
The pool is a want, not a need, but in this market it is an option your budget actually reaches.
Your Equity Is a Down Payment on a Different Life
Here is an illustrative example, run plainly. A California home sells for $1.2 million with a mortgage payoff near $500,000, leaving roughly $700,000 of gross equity before selling costs and taxes. To make the example concrete, assume total selling costs—including any brokerage compensation and other seller-side transaction costs—equal 6 to 7 percent of the sale price. That assumption would equal roughly $72,000 to $84,000, leaving approximately $616,000 to $628,000 before any income-tax consequences. Actual brokerage compensation is negotiable and not set by law, and other seller costs vary by transaction, so a California seller should obtain a property-specific estimated net sheet rather than treating 6 to 7 percent as a standard charge.
Now look at what that cash does in the Hill Country. The point is not that you must spend all of it. The point is that it buys you a choice that California stopped offering.
Buy at $550,000
All cash, no mortgage
Using approximately $622,000 as the midpoint of the illustrative California net-proceeds range, a $550,000 cash purchase leaves about $72,000 before Texas buyer closing costs, moving expenses and any reserve you choose to maintain. No payment at all, tax and insurance excepted. This is the mortgage-free-housing version of the math.
Buy at $750,000
20% down, substantial liquidity preserved
Using the same $622,000 midpoint, a $150,000 down payment leaves about $472,000 before Texas buyer closing costs, moving expenses and reserves. A $600,000 30-year mortgage is approximately $4,000 per month in principal and interest at 7.03 percent. Newer, bigger, while retaining substantial liquidity outside the home.
Buy at $950,000
20% down, one bigger house
Using the same $622,000 midpoint, a $190,000 down payment leaves about $432,000 before Texas buyer closing costs, moving expenses and reserves. A $760,000 30-year mortgage is approximately $5,070 per month in principal and interest at 7.03 percent, before property tax, homeowners insurance, HOA charges or other property-specific costs. Estate territory on an acre or more.
The $800,000 band in the tables above, with its acre lots, gated sections, and pools, is where this equity lands most comfortably; the $1.2 million estates are within reach with a larger mortgage or a larger California sale. If your California sale produces more net equity after the mortgage payoff, transaction costs and any applicable taxes, these purchase options expand. One caution: the tax side of the sale is real. California real-estate withholding generally applies unless the seller certifies an applicable exemption on Form 593. When no exemption applies, the standard sales-price method is 3⅓ percent, although an alternative withholding calculation may be available. A qualifying principal-residence transaction may be exempt. Withholding is a tax-payment mechanism, not necessarily the seller's final California income-tax liability, so the seller's CPA should separately evaluate basis, taxable gain and eligibility for the federal Section 121 exclusion.
Renter? Your First Year of Owning Is Closer Than You Think
This section is for the family that rents in California, watches the rent compound, and assumes ownership is for other people. Here is the plain version of the math.
First, you already have a payment history. A two-bedroom in San Jose runs about $3,234 a month by Apartment List's September 2026 estimate [15]. Los Angeles city's August two-bedroom median was about $2,367 [16], while higher-cost Westside and nearby markets run materially higher. Newport Beach, as a coastal Orange County reference point, averaged about $4,357 for a two-bedroom [17]. Lenders look at income, credit, debts, and how you have actually handled a monthly housing obligation. Your rent record is part of that proof, not all of it.
Second, the down-payment hurdle may be smaller than you think—but it is not the entire cash-to-close requirement. At 3.5 percent down (FHA) a $450,000 to $550,000 home needs roughly $16,000 to $19,000; at 3 to 5 percent (conventional) it needs roughly $14,000 to $28,000. Compare that with the $200,000 to $300,000 that 20 percent down on a Bay Area entry home demands. One limit to know: the 2026 national FHA one-unit floor is $541,287. For the San Antonio–New Braunfels MSA, the 2026 one-unit limit is $557,750 in Bexar, Comal, Guadalupe, Kendall, Bandera and the other counties in that MSA. Kerr County remains at the $541,287 national floor. FHA limits are county-specific and updated annually, so have your lender verify the limit for the exact property before relying on it. Texas homebuyer-assistance programs, including TSAHC down-payment assistance, can cover part of the gap for eligible borrowers. TSAHC's Home Sweet Texas program serves qualifying first-time and repeat home buyers, subject to current program, income, credit and lender requirements. I am a TSAHC Participating Realtor for 2026, which means I work these programs, not just mention them. The grant guidance page and the first-time buyer program guide walk through the options.
Down payment is not the same thing as cash to close. Buyers also need to budget for lender and settlement charges, prepaid taxes and insurance, inspections, and any required reserves. Freddie Mac says closing costs generally run about 2 to 5 percent of the purchase price [36], although seller concessions, lender credits, and down-payment-assistance programs can reduce what a particular buyer must bring to closing. Ask a lender for a Loan Estimate before treating the down-payment number as the total amount of cash required.
Third, the monthly number is close to what you already pay, though usually somewhat higher. At the 7.03 percent Freddie Mac benchmark reported September 24, 2026, a $450,000 to $550,000 purchase with 5 to 10 percent down can produce an all-in monthly housing payment roughly in the high-$3,000s to low-$5,000s once principal, interest, estimated property tax, homeowners insurance and mortgage insurance are included. The actual number can move materially with the tax jurisdiction, insurance quote, credit profile, loan program and down payment. Using Apartment List's approximately $3,234 San Jose two-bedroom median as the reference point, that illustrative Texas payment runs roughly several hundred dollars to nearly $2,000 higher. The same Texas payment range overlaps Newport Beach's approximately $4,357 two-bedroom average. If you rent here first, Boerne two-bedroom rents average around $1,437 [27], which gives you room to save while you shop.
WHAT THE MONTHLY COMPARISON CAN MISS
The mortgage payment is only part of the ownership budget. Depending on the property, also account for HOA dues, MUD taxes or PID assessments, flood insurance, utilities, routine maintenance, major-system replacement and the cash required at closing. A larger Texas home can also cost more to cool, furnish, landscape and maintain than the California home or apartment it replaces.
Freddie Mac's weekly benchmark reflects a conventional owner-occupied purchase profile with good or excellent credit and approximately 20 percent down. A borrower putting 5 or 10 percent down may receive a different rate and will generally have mortgage insurance, so this is an illustration rather than a loan quote.
Fourth, the timeline is real. Rent month-to-month or short-term when you arrive, get your post-move employment or income documentation, credit, cash-to-close and residency logistics lined up, and determine with a lender when you are actually mortgage-ready. Some buyers can purchase within their first year; others benefit from renting longer. Once under contract, financed purchases commonly take several weeks to close; Freddie Mac currently cites an average purchase-loan closing time of about 43 days [40], and a good agent can stagger your close around a lease. Many of the families I work with time their Texas closing to land in the final weeks of their California lease, which keeps the overlap to days, not months. One more year-one surprise: if you buy new construction, your first tax bill may be based on partly improved land. When the finished house is appraised, the escrow payment can jump in year two. Model your payment on the fully improved value, not the tax certificate at closing.
The honest line: owning means maintenance, taxes, insurance and more responsibility. For some high-rent California households the Texas payment may be surprisingly close to current rent; for others it will be materially higher. The useful comparison is not rent versus principal and interest—it is current rent versus the complete ownership payment and the additional space, control and equity that payment purchases.
Three Ways to Read the Same Numbers
Budget by what you get, land by the numbers, and the firsts your money buys. Same story, told three ways.
Budget by what you get
| Budget | The Hill Country headline | Typical size | Typical lot | The honest tradeoff |
|---|---|---|---|---|
| $600,000 | Middle of the market, picky shopping | 1,900-3,400 sq ft | 0.25-1 acre | Not every house is new; location does the deciding |
| $800,000 | Upper tier of the mainstream: acre, pool, gated | 2,600-3,800 sq ft | 0.5-1+ acre | HOA dues, plus MUD or PID taxes in some master plans |
| $1,200,000 | Upper-tier market: custom estates, premium outdoor improvements or guest accommodations | 3,200-5,500 sq ft | 1-5+ acres | Maintenance scale goes up with the house |
Illustrative lot-size patterns: California versus the Hill Country
| Housing type | Typical California lot (Bay Area / Westside / coastal OC) | Typical Hill Country lot |
|---|---|---|
| Condominium or townhouse | Typically little or no individually owned lot; attached units often have shared walls and limited private outdoor space | Less common in these six Hill Country communities than detached single-family housing |
| Single-family starter | Compact lots in the dense coastal markets examined here, commonly measured in thousands of square feet rather than acres | Detached homes on lots commonly measured in fractions of an acre; newer master-planned phases sit at the smaller end [26] |
| Family home | Larger lots than starter homes, still measured in thousands of square feet in the coastal markets examined here | 0.5-1 acre in established neighborhoods, many at the full acre [26] |
| Upscale or master-planned | Larger urban and suburban lots, still well below the acreage common in the Hill Country | 0.5-1.5 acres in gated and estate sections [26] |
| Custom estate | Large urban lots exist, but acreage is comparatively scarce in the dense coastal markets examined here | 1-10 acres, common at the estate price point [26] |
Acreage comes with its own checklist. Some acreage properties rely on private wells and septic systems rather than public water and sewer, so verify the utility configuration for the exact property, which can add testing, pump maintenance and septic-inspection responsibilities that may be unfamiliar to buyers coming from urban and suburban California. Some larger parcels carry an agricultural or wildlife valuation that lowers the tax bill; ask what it takes to keep it and what a change in use would trigger. If you plan to use state down payment assistance, note that TDHCA generally limits the land counted with the home to one acre [41]. TDHCA guidance can allow an exception when a larger lot is customary for the area, is not being used to produce income, and otherwise satisfies program requirements. Confirm acreage eligibility with the participating lender before assuming a property qualifies. The water and infrastructure guide covers wells, septic, and water rights in detail.
This acreage provision is specific to the applicable TDHCA program guidance. TSAHC and other assistance programs have their own property-eligibility rules, so verify the requirements of the specific program being used.
The firsts your money buys
Your first extra bedroom
The one that is not the office, not the baby's room, not the junk room, just an empty room with a door. It does not sound like much until you have one.
Your first real yard
Grass your kids can play on, a swing set that stays up all season, a dog that gets to be a dog. Yards measured in acres do not need defending.
Your first three-car garage
Room for both cars, the bicycles, the tools, and the box of things you meant to unpack. Some lots also fit a shop, a boat, or a trailer.
Your first guest suite
A bed, a bath, and a door that closes, so the people you love can visit for a week instead of a weekend. This is the one grandparents notice first.
The Table People Save
Same budget, two states. Save this, screenshot it, send it to the person who insists the Bay Area is the only place to build a life.
| Your budget | California gets you | Texas Hill Country gets you |
|---|---|---|
| $600,000 | A condominium, townhouse or smaller/older property in the California markets examined here, with competition varying substantially by submarket [11][12][13] | A 1,900-3,400 sq ft house on a quarter-acre to an acre, three or four bedrooms, attached garage, and a yard [1][4][5][6][7][8][9][10][39] |
| $800,000 | A condo or townhouse, or a small, dated detached house with the renovation list included in the price [11][12][13] | A 2,600-3,800 sq ft new or near-new home on a half-acre or more, with an office, a garage, and a pool that can be within reach [1][2][3] |
| $1,200,000 | Below the San Jose median: an older house that still needs attention, with competition varying substantially by submarket [11] | A 3,200-5,500 sq ft custom home on one to five acres or more; examples may include guest quarters, a pool, or premium outdoor improvements or guest accommodations [1][2][10] |
Save This Page
This is the page to reopen when the California-versus-Texas housing discussion turns from purchase price to the full carrying cost. Bookmark it and revisit the figures as prices, mortgage rates, taxes, insurance and your own circumstances change.
The one-page version
- Under the article's stated mortgage, tax and insurance assumptions, the modeled monthly cost of a three- or four-bedroom Hill Country house can run somewhat above the current San Jose two-bedroom median rent [14][15].
- $600K: 1,900-3,400 sq ft on a quarter-acre to an acre. $800K: 2,600-3,800 sq ft on a half-acre or more. $1.2M: a 3,200-5,500 sq ft custom home, with lots that may run one to five acres or more [1][2][10].
- About $622,000 in net sale proceeds, under the illustrative 6 to 7 percent selling-cost assumption, buys a $550,000 Hill Country home outright, or puts 20 percent down on a $950,000 home with roughly $432,000 remaining before Texas buyer closing costs, moving expenses and reserves.
- Renters: the down payment gate is 3 to 5 percent, with closing costs and other cash-to-close requirements on top, and the total payment runs somewhat above San Jose two-bedroom rent and in line with beach-city Orange County rent, so year-one ownership may be realistic for a qualified buyer whose income, credit, debt profile and cash-to-close support it [14][15][17].
- The four caveats that keep the win honest: a broad property-tax planning range of roughly 1.7-2.1% of market value before exemptions, with property-specific taxing units, MUD taxes or PID assessments affecting the actual carrying cost, insurance averaging about $3,489 a year before any flood policy [22], the real summer heat, and the distance from family.
- File the residence homestead exemption after you close: $140,000 in general school-district exemption, plus an additional $60,000 for qualifying homeowners aged 65 or older or disabled. Quote insurance three times before you commit, and verify school-district assignment by address [21][25].
Educational summary; figures are approximate ranges from the sources cited below and change with the market. Verify anything you rely on before acting.
The Pillar Pages That Go Deeper
This article compresses the decision into three budgets. The full versions of each column, with more tables and more math, live on these four pages.
California vs Texas cost of living
Housing, taxes, insurance, utilities, fuel, and groceries side by side, with the annual-savings ranges [24].
Open the comparisonProp 13 vs Texas property tax
Assessment caps compared with the $140,000 homestead exemption, the 10 percent cap, and the protest process [23].
Open the tax guideSchools and education
Boerne ISD, Comal ISD, and Northside ISD ratings, funding, transfers, and how Texas schools compare with California [25].
Open the schools guideNeighborhoods and communities
Boerne and Fair Oaks Ranch, subdivision by subdivision, with price ranges, lot sizes, HOAs, and schools [26].
Open the community guideNOT MOVING FROM CALIFORNIA?
The same framework works from any origin state, but the tax, housing and equity math changes materially. Start with your current housing cost, expected sale proceeds or rent, state-income-tax treatment and the exact Texas property you are considering rather than assuming the California comparison applies to you.
Frequently Asked Questions
The questions that come up every time a California buyer runs this arithmetic for real, answered the way I would answer them across a kitchen table.
Is it really true that my monthly payment could stay the same or go down?
Sometimes. For a renter paying something near Newport Beach's current two-bedroom average, the modeled Texas ownership-payment range can overlap current rent. For a renter near San Jose's current two-bedroom median, the Texas ownership payment would generally be higher under these assumptions. For a San Jose renter, expect it to go up somewhat. The comparison that matters is the one you already live. A two-bedroom apartment in San Jose rents for roughly $3,200 to $3,600 a month [15]. A $450,000 to $550,000 Hill Country home at the 7.03 percent average reported September 24, 2026 [14], with 5 to 10 percent down, carries a total payment of roughly $3,750 to $5,000 a month including principal, interest, property tax, insurance, and mortgage insurance. That is somewhat more than the San Jose rent, and it buys three or four bedrooms, a yard, and equity building every month. The catch is the column people skip: property tax and insurance run higher in Texas, so the fine print lives in the tax guide [23] and a real insurance quote [22].
Won't Texas property taxes eat the savings?
They are one of the largest recurring costs to model carefully. For initial planning, I use roughly 1.7 to 2.1 percent of market value per year before exemptions as a broad Hill Country screening range. Actual tax is based on the property's taxable value and the rates imposed by its specific taxing units, and some developments also carry MUD taxes or PID assessments.
Texas school districts must provide a $140,000 general residence-homestead exemption. A homeowner who qualifies as age 65 or older or disabled receives an additional $60,000 school-district exemption. For a qualifying residence homestead, the appraisal limitation generally restricts annual growth in appraised value to 10 percent, subject to the statutory rules governing when the limitation begins and how new improvements are treated. You can also protest an appraisal you believe is incorrect.
What about insurance? Does fire or flood change the picture?
Yes, and this is where a spreadsheet gets honest. Texas homeowners insurance averaged $3,489 per year statewide in 2025 according to the Texas Department of Insurance. That is a statewide average, not a quote for a particular Hill Country property. TDI reports that wind and hail have accounted for an average of roughly 62 percent of homeowners paid losses since 2019. Wind and hail deductibles can differ from other covered-loss deductibles and may be stated as either dollar amounts or percentages, depending on the policy. Standard homeowners insurance generally does not cover flood damage.
Hill Country rivers can rise rapidly, as the July 2025 flooding in Kerr County demonstrated. Check the FEMA flood map for the exact address and obtain a property-specific flood quote. NFIP coverage ordinarily has a 30-day waiting period, but important exceptions apply, including coverage purchased in connection with making, increasing, extending or renewing a mortgage. Wildfire exposure also varies by property, especially on wooded acreage. Obtain property-specific quotes before the option period ends.
How hot is it, really?
Genuinely hot, and you should not pretend otherwise. June through September is a real season here, the air conditioning runs hard, and the summer electric bill surprises newcomers even when they expected it. Buy a house with good insulation and shade, budget the utility line, and plan outdoor life for morning and evening. The heat is a fact of the trade; it is not a hidden fee.
Is Fair Oaks Ranch worth the premium over Boerne?
It depends on what you are buying. Zillow's August 31, 2026 ZHVI puts the typical Fair Oaks Ranch home at approximately $702,500, compared with approximately $557,400 in Boerne. Fair Oaks Ranch offers many larger-lot, golf-oriented and gated options, while Boerne offers deeper inventory and proximity to its walkable downtown core. Those market-value differences partly reflect differences in the housing stock, so do not treat the gap as the price of any one amenity.
Can I buy in Texas before I sell in California?
Yes, with planning. Options include a bridge or HELOC strategy on the California side, a longer Texas closing, or the synchronized approach where both closings land on the same week with the two agents talking directly. Coordinating a California sale with a Texas purchase is the core of my relocation work; the interstate playbook walks through the mechanics.
How should I evaluate the school districts?
Boerne ISD reports seven consecutive A ratings from the Texas Education Agency, one of the longest streaks in the state [18][19]. Comal ISD, which serves Bulverde and much of the growth around New Braunfels, is rated B [20]; New Braunfels ISD, which serves much of central New Braunfels, is also rated B [28]. Helotes and some Fair Oaks Ranch parcels fall to Northside ISD, a large San Antonio district rated C overall in 2026, where campus ratings vary widely [29]. The right answer is a specific address, not a town name, because district boundaries follow parcels, and the schools guide covers the evaluation process in order [25].
I'm a renter, not a homeowner. Is this article for me?
It is written partly for you. The payment you already make in California rent provides useful context, but a lender will qualify you based on income, debts, credit, assets, loan program and other underwriting requirements. Eligible low-down-payment loan programs can permit roughly 3 to 5 percent down, depending on the loan program. By comparison, a 20 percent down payment on a $1 million to $1.5 million Bay Area home would require $200,000 to $300,000. In either case, the down payment is not the complete cash-to-close requirement. The year-one ownership section near the middle of this article is the plain version of how that math works, including Texas homebuyer-assistance programs.
What to Do Next
If this article changed the shape of the map for you, the next step is not a sales call. It is a conversation. The Start Here page walks you through building your move plan in order, and the city comparison page lays the six communities side by side. When you are ready to talk specifics, the offer is simple: a no-pressure conversation about your situation, your numbers, and your timeline. I have watched dozens of families run this exact arithmetic, and the hard parts are almost always personal and logistical, not hidden line items. That is why I put the numbers on the page first.
Bill Ross at Hill Country Homesteads Group, brokered by Keller Williams Boerne, coordinates California-to-Texas purchases through a direct network of more than 1,100 California real-estate agents, so the two closings can be coordinated to land in the same week and keep double-mortgage exposure to a minimum. Reach me through the contact page, by email at Bill@HillCountryHomesteads.com, or by phone at (210) 294-9190 during business hours, 8 AM to 6 PM Central, Monday through Friday. The brokerage is at 116 Herff Rd, Suite 203, Boerne, TX 78006.
The same framework lives across the two sister sites: hillcountryhomesteads.com carries the Boerne and Kendall County market work, and texasprobatehomes.net covers the estate and probate side of a cross-state move, for the families whose decision includes a property that has already been in the family for a generation.
Sources
Official and primary sources are used for tax, insurance, mortgage, flood, school and program rules wherever available. Housing prices, rents and other market measures rely on the dated market-data sources identified below. Different providers use different methodologies, so each statistic should be read as the measure identified rather than as an interchangeable market value.
- Boerne, TX housing market : Redfin, three-month median sale price approximately $505,000 through August 2026; Boerne medians across recent months have run roughly $450,000 to $665,000 depending on the neighborhood and period. www.redfin.com/city/2371/TX/Boerne/housing-market
- Fair Oaks Ranch, TX housing market : Redfin, three-month median sale price approximately $718,524 through August 2026. www.redfin.com/city/6483/TX/Fair-Oaks-Ranch/housing-market
- Fair Oaks Ranch, TX home values : Zillow Home Value Index (ZHVI), typical home value approximately $702,497 as of August 31, 2026. www.zillow.com/fair-oaks-ranch-tx/
- Helotes, TX housing market (78023) : Zillow typical home value (ZHVI) approximately $466,276 as of August 31, 2026. www.zillow.com/home-values/21813/helotes-tx/
- Helotes, TX housing market, three-month median : Redfin median sale price approximately $442,207 over the three months ending August 2026. www.redfin.com/city/8471/TX/Helotes/housing-market
- Bulverde, TX housing market : Redfin, three-month median sale price approximately $864,282 through August 2026. Short-period transaction medians can be volatile in smaller markets and should not be treated as equivalent to Zillow ZHVI. www.redfin.com/city/2901/TX/Bulverde/housing-market
- Bulverde, TX home values : Zillow Home Value Index (ZHVI), typical home value approximately $476,306 as of August 31, 2026. www.zillow.com/home-values/3887/bulverde-tx/
- New Braunfels, TX housing market : Redfin median sale price approximately $347,000 over three months ending August 2026 (secondary: PropertyFocus median about $344,000). www.redfin.com/city/13081/TX/New-Braunfels/housing-market
- New Braunfels, TX home values : Zillow, typical home value (ZHVI) approximately $346,475, data through August 31, 2026. www.zillow.com/home-values/39966/new-braunfels-tx/
- Kerrville, TX home values : Zillow, typical home value (ZHVI) approximately $354,027, data through August 31, 2026. www.zillow.com/home-values/12186/kerrville-tx/
- San Jose, CA housing market : Redfin median sale price approximately $1.4 million and median $858 per square foot over three months ending August 2026; about half of sales closed above list price. www.redfin.com/city/17420/CA/San-Jose/housing-market
- Westside, Los Angeles housing market : Redfin, median sale price approximately $1.9 million and median $888 per square foot over three months ending August 2026; neighborhood medians vary widely. www.redfin.com/neighborhood/3020/CA/Los-Angeles/Westside/housing-market
- Orange County, CA housing market : Redfin countywide median sale price approximately $1.2 million and median $676 per square foot over three months ending August 2026; coastal cities run well above county figures; some single-family county medians run higher (secondary: California Association of Realtors, Orange County median sold price for existing single-family homes approximately $1,452,500 in August 2026). www.redfin.com/county/332/CA/Orange-County/housing-market
- Primary Mortgage Market Survey : Freddie Mac, U.S. average 30-year fixed-rate mortgage 7.03 percent as of September 24, 2026, the most recent weekly reading before publication. The survey reflects 20 percent down and excellent credit; lower-down-payment loans may price differently. www.freddiemac.com/pmms
- San Jose, CA rent report : Apartment List, two-bedroom median rent approximately $3,234 per month, September 2026 (secondary sources range to about $3,600). www.apartmentlist.com/rent-report/ca/san-jose
- How much is rent in Los Angeles? : Apartment List, renter-life article dated August 2026: Los Angeles two-bedroom median rent approximately $2,367 per month, consistent with Apartment List's September 2026 Los Angeles rent report. www.apartmentlist.com/renter-life/how-much-is-rent-in-los-angeles
- Newport Beach, CA rent report : RentCafe, average two-bedroom rent approximately $4,357 as of August 31, 2026. www.rentcafe.com/average-rent-market-trends/us/ca/newport-beach/
- 2026 Texas A-F accountability ratings : Texas Education Agency, released August 14, 2026; Boerne ISD overall A (score 92), Comal ISD overall B (score 88), New Braunfels ISD overall B (score 84), Northside ISD overall C. tea.texas.gov/about-tea/newsroom/tea-releases-2026-f-accountability-ratings-txschoolsgov
- Boerne ISD, seven consecutive A ratings : Boerne ISD: official district page reporting seven consecutive A ratings from the Texas Education Agency and identifying Boerne ISD as one of 31 Texas districts to accomplish that record. www.boerneisd.net/enroll
- Comal ISD 2026 accountability rating : Texas Education Agency, 2026 accountability release: Comal ISD overall B, score 88. tea.texas.gov/about-tea/newsroom/tea-releases-2026-f-accountability-ratings-txschoolsgov
- Schools, City of Fair Oaks Ranch : Official city page documenting that Fair Oaks Ranch spans Kendall, Bexar, and Comal counties and is served primarily by Boerne ISD, with Northside ISD and Comal ISD serving some parcels by address. www.fairoaksranchtx.org/59/Schools
- Texas homeowners insurance market overview : Texas Department of Insurance, statewide average homeowners premium of $3,489 for 2025; statewide average only, not a property-specific Hill Country quote. www.tdi.texas.gov/general/texas-homeowners-insurance-market-overview.html
- Proposition 13 vs Texas Property Tax : MoveToTexas.net pillar page (secondary): homestead exemption, the 10 percent appraisal cap, tax protest, and millage context. movetotexas.net/prop-13-vs-texas-tax/
- California vs Texas Cost of Living : MoveToTexas.net pillar page (secondary): housing, taxes, insurance, utilities, fuel, and groceries side by side. movetotexas.net/real-cost-comparison/
- Schools and Education in the Texas Hill Country : MoveToTexas.net pillar page (secondary): district ratings, funding, transfers, and enrollment. movetotexas.net/schools-education/
- Boerne and Fair Oaks Ranch Neighborhoods: Where to Live : MoveToTexas.net pillar page (secondary): community-by-community profiles and price ranges. movetotexas.net/neighborhoods/
- Boerne, TX rent trends : Rent.com, two-bedroom average rent approximately $1,437 per month, a secondary comparison point for the renter math. www.rent.com/texas/boerne-apartments/rent-trends
- New Braunfels ISD 2026 accountability rating : Texas Education Agency, 2026 accountability release: New Braunfels ISD overall B, score 84. tea.texas.gov/about-tea/newsroom/tea-releases-2026-f-accountability-ratings-txschoolsgov
- Northside ISD 2026 accountability rating : Texas Education Agency, 2026 accountability release: Northside ISD overall C. tea.texas.gov/about-tea/newsroom/tea-releases-2026-f-accountability-ratings-txschoolsgov
- Kerrville ISD accountability rating : Kerrville ISD accountability rating: official district page reporting an overall B rating in 2026, the district's third consecutive B rating. www.kerrvilleisd.net/our-district/required-postings/accountability-rating
- FEMA Flood Map Service Center : official flood-zone lookup by address. msc.fema.gov/portal/home
- Buy a Flood Insurance Policy : National Flood Insurance Program / FloodSmart, official page on the 30-day waiting period and its exceptions, including coverage purchased in connection with a mortgage. www.floodsmart.gov/get-insured/buy-a-policy
- Residence homestead exemptions : Texas Comptroller of Public Accounts, property tax exemptions: the mandatory $140,000 school-district residence homestead exemption plus the additional $60,000 exemption for qualifying homeowners aged 65 or older or disabled. comptroller.texas.gov/taxes/property-tax/exemptions/
- Residence homestead appraisal limitation : Texas Comptroller of Public Accounts: the appraised value of a residence homestead may not increase more than 10 percent per year, subject to the statutory rules for when the limitation begins and for new improvements. comptroller.texas.gov/taxes/property-tax/valuing-property.php
- FHA mortgage loan limits : U.S. Department of Housing and Urban Development: 2026 FHA single-family mortgage limits, including the national one-unit floor of $541,287, with county-specific limits and annual updates; official 2026 Areas Above Floor and Below Ceiling table at https://www.hud.gov/sites/dfiles/SFH/documents/FHA-2026-Areas-Above-Floor-and-Below-Ceiling.pdf. www.hud.gov/news/hud-no-25-145
- Understanding homebuying costs : Freddie Mac, My Home: consumer guidance on up-front and closing costs of buying a home. myhome.freddiemac.com/buying/understanding-costs
- 2026 Instructions for Form 593 : California Franchise Tax Board: Form 593 instructions covering real-estate withholding, certified exemptions, and the alternative withholding calculation for 2026. www.ftb.ca.gov/forms/2026/2026-593-instructions.html
- Compensation, commission and concessions : National Association of Realtors: real-estate brokerage commissions are negotiable and not set by law; NAR does not dictate commissions. www.nar.realtor/news/real-estate-news/sales-marketing/compensation-commission-and-concessions
- Boerne, TX home values : Zillow Home Value Index (ZHVI), typical home value approximately $557,428 as of August 31, 2026. www.zillow.com/home-values/8154/boerne-tx/
- Closing your home purchase : Freddie Mac My Home, reporting an average purchase-loan closing time of 43 days. myhome.freddiemac.com/buying/closing-your-loan-when-buying
- TDHCA Homebuyer Program Lender Guide : Texas Department of Housing and Community Affairs, Lender Guide effective August 26, 2026: land appurtenant to a residence is generally limited to one acre, with an exception when a larger lot is customary for the area and is not being used to generate income. welcomehome.tdhca.texas.gov/uploads/Lender-Guide.pdf
Last verified: September 30, 2026. Medians, rates, and rents are the published readings referenced above and will shift with the market; refresh them against current local sources before relying on the figures. Composite homes are illustrative shopping profiles assembled from current and recent market inventory, not listings. Confirm anything time-sensitive with the local multiple listing service, the appraisal district, the Texas Department of Insurance, your lender, and a tax professional. This is general educational information about real estate, not legal, tax, or financial advice. Bill Ross is available at (210) 294-9190 during business hours, 8 AM to 6 PM Central, Monday through Friday.